VA Home Buying in Imperial Beach: Military Guide
VA Home Loans, Imperial Beach Real Estate, Military Home Buying
VA Home Buying in Imperial Beach: A Guide for Military Buyers
Thinking about putting down roots near the sand, surf, and bases of San Diego? Imperial Beach offers a rare mix of coastal living and military convenience, and VA home loans can make buying here far more attainable than many service members realize. This guide walks you through the Imperial Beach housing market, how VA benefits work, and practical home buying tips tailored to military buyers.
Why Imperial Beach Appeals to Military Homebuyers
Imperial Beach sits at the southern edge of San Diego County, just minutes from Naval Base Coronado, Naval Base San Diego, and other key installations. For active-duty service members and veterans, it offers a shorter commute, a relaxed beach-town feel, and comparatively more affordable coastal prices than many nearby neighborhoods.
As of summer 2026, the Imperial Beach housing market is showing moderate stability with home prices typically ranging from the low $800,000s to mid-$800,000s, depending on the source and property type. Redfin reports a median sale price around $852,000 with prices up roughly 3.3% year-over-year, while Zillow’s home value index is near $858,700 with a 2.1% annual increase. Realtor.com notes a median sold price of about $800,000 and considers the area a slight buyer’s market, with homes selling around 99% of list price.
Inventory has climbed; Realtor.com reports more than a 30% year-over-year increase in active listings, giving buyers more choice and room to negotiate. For military home buying, that combination of coastal lifestyle, strong long-term equity, and a bit more leverage at the negotiation table is compelling, especially when paired with VA home loan benefits.
Understanding VA Home Loans: Core Benefits for 2026
VA home loans are one of the most powerful tools available to eligible service members, veterans, and some surviving spouses. Backed by the U.S. Department of Veterans Affairs, they are designed to make homeownership more accessible and affordable. According to the VA, key benefits include:
No down payment in most cases: Qualified buyers can often finance 100% of the purchase price, which is especially helpful in higher-cost markets like Imperial Beach real estate.
Competitive interest rates: VA loans typically offer lower rates than many conventional loans, helping keep monthly payments manageable even as prices rise.
No private mortgage insurance (PMI): With conventional loans, putting less than 20% down usually means PMI. VA loans avoid this cost, saving hundreds of dollars per month for some borrowers.
Limited closing costs: The VA caps certain fees and allows sellers to contribute toward closing costs, which can be a valuable negotiation point in your offer.
Flexible credit guidelines: The VA itself does not set a hard minimum credit score, though individual lenders will. Overall, guidelines are often more forgiving than with some conventional products.
There is a VA funding fee, which helps keep the program running, but it can usually be rolled into the loan amount instead of being paid upfront. Certain buyers, such as those with service-connected disabilities, may be exempt from this fee. For the most current details on funding fees and eligibility, the official VA Benefits Guide at VA.gov is the best reference.
Eligibility Basics: Who Can Use a VA Home Loan?
VA home loans are available to a broad range of military-connected borrowers, including:
Active-duty service members with sufficient service time
Veterans who meet minimum service requirements
Certain members of the National Guard and Reserves
Some surviving spouses of service members who died in the line of duty or from service-connected causes
To use your benefit, you’ll need a Certificate of Eligibility (COE), which your lender can often request electronically. As part of your VA benefits guide, a knowledgeable lender should walk you through how your entitlement works, what your loan limits look like in San Diego County, and how much you can comfortably afford in the Imperial Beach housing market.
Imperial Beach Housing Market Snapshot for Military Buyers
Current real estate trends in Imperial Beach show a market that is competitive but not overheated. Depending on the source and time of year, median sale prices range from about $820,000 to the mid-$800,000s, with some peak months reaching even higher for prime coastal properties. Redfin notes homes selling in a median of 27 days, while other sources place typical days on market closer to 50, suggesting that well-priced homes move quickly while others sit longer and invite negotiation.
Inventory is up significantly over 30% year-over-year in some reports, which is good news for VA buyers. More listings mean more options in different neighborhoods, from bayside condos to single-family homes near Calla and Donax Streets. Property Focus data shows strong equity positions and very low distress rates, suggesting Imperial Beach real estate is generally stable and resilient over time, a positive sign if you’re thinking about long-term ownership or eventual resale when you PCS.
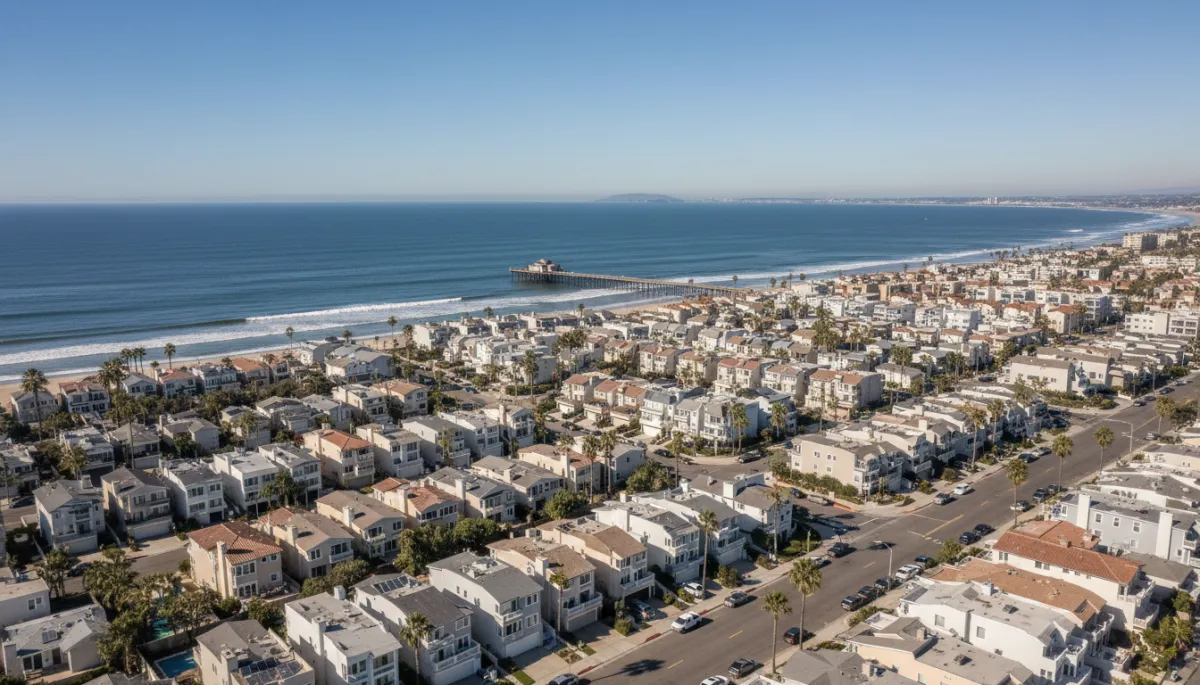
Rising inventory and stable prices give VA buyers more leverage and choice.
Key Home Buying Tips for Military Families in Imperial Beach
1. Start with Your Budget and BAH
Before you fall in love with a beach bungalow, map out your monthly comfort zone. Consider your Basic Allowance for Housing (BAH), other income, and recurring obligations. A skilled VA lender can show you how your BAH translates into a realistic price range for Imperial Beach real estate, factoring in taxes, insurance, and any homeowners association (HOA) dues for condos or townhomes.
2. Get Preapproved with a VA-Experienced Lender
In a market where desirable homes can still sell in under a month, a VA preapproval letter is essential. It not only clarifies your price range but also signals to sellers that you’re serious and qualified. Look for a lender who regularly works with VA home loans in San Diego County and understands local appraisals, VA property standards, and timelines around PCS orders and deployment schedules.
3. Work with an Agent Who Knows VA and the Bases
Military home buying has its own rhythm. You may be house-hunting from out of state, under tight timelines, or balancing deployment schedules. Partner with a real estate agent who:
Understands VA loan requirements and can flag properties that may have issues with VA appraisals or minimum property standards
Knows commute times to Naval Base Coronado, Naval Base San Diego, and other commands
Has experience negotiating seller credits toward closing costs, which can further stretch your VA benefits
4. Consider Resale and PCS Flexibility
Even if you plan to stay for years, it’s smart to think like an investor. The Imperial Beach housing market has strong rental demand, with average rents in the mid-$3,000s and solid year-over-year growth. If you receive PCS orders, you may be able to:
Sell into a stable coastal market with historically resilient prices, or
Convert your home into a rental, potentially covering your mortgage and building equity while you’re stationed elsewhere
5. Use Your VA Benefits Guide as a Checklist
As you move through the process, treat your VA benefits as a built-in checklist. Are you maximizing your no-down-payment option? Have you explored whether you qualify for a funding fee exemption? Are you taking advantage of seller-paid closing costs where possible? Reviewing the official VA Benefits Guide and discussing it with your lender and agent ensures you’re using every advantage available.
How to Compete Effectively in the Imperial Beach Market with a VA Loan
Some buyers worry that VA financing will make their offer less attractive than conventional offers. In practice, a well-structured VA offer can be very competitive, especially in a market that is edging toward buyers’ favor. Here are a few strategies:
Strong preapproval: Provide a fully underwritten preapproval letter, not just a prequalification, to show you’ve already passed an in-depth review.
Flexible timelines: If your schedule allows, offer a closing date that suits the seller, or be open to a short rent-back agreement if they need extra time to move.
Clean terms: Avoid unnecessary contingencies while still protecting yourself with key inspections and appraisal protections built into the VA program.
Is Now a Good Time for Military Buyers to Purchase in Imperial Beach?
While no one can predict the future with certainty, the data for 2026 paints a cautiously optimistic picture. Prices have shown modest year-over-year growth, inventory is higher than last year, and the broader Imperial Beach housing market leans slightly toward buyers in many segments. At the same time, strong homeowner equity and low distress levels suggest that the area is not at high risk for a steep downturn, especially for well-located properties near the coast and key amenities.
For military buyers using VA home loans, this environment can be especially favorable. You’re able to leverage no-down-payment financing in a market where sellers are increasingly open to negotiation, while still purchasing in a community with long-term appeal, strong rental demand, and proximity to major bases.
Bringing It All Together: A Practical Path to Your Imperial Beach Home
VA home buying in Imperial Beach doesn’t have to feel overwhelming. Start by understanding your VA benefits, then connect with a VA-savvy lender and a local agent who regularly works with military families. Use current market data to set realistic expectations around price, competition, and timelines, and keep your long-term plans in mind, whether that means living in your home for one tour or turning it into a future rental when you receive new orders.
With the right guidance, your VA benefits guide becomes more than paperwork, it becomes a roadmap to owning a piece of Imperial Beach real estate that fits your lifestyle, supports your financial goals, and keeps you close to the mission you serve.
Frequently Asked Questions About VA Home Buying in Imperial Beach
Can I use a VA loan to buy a condo in Imperial Beach?
Yes, you can use a VA loan to purchase a condo, as long as the condominium project is approved by the VA. Your lender or real estate agent can help you verify whether a specific Imperial Beach condo community is on the VA-approved list or walk you through the steps to seek approval.
Do I have to live in the home if I buy with a VA loan?
VA loans are intended for primary residences, so you’ll need to certify that you plan to occupy the home, typically within 60 days of closing. Later, if you receive PCS orders, you can usually convert the property to a rental while keeping your existing VA financing in place, as long as you met the initial occupancy requirement.
Can I use my VA loan benefit more than once?
In many cases, yes. Your VA entitlement can be restored after you sell a home and pay off the VA loan, and in some situations you may even have enough remaining entitlement to hold more than one VA loan at a time. A VA-experienced lender can review your Certificate of Eligibility and explain how much entitlement you have available for an Imperial Beach purchase.
What out-of-pocket costs should I expect with a VA loan?
Even with no down payment, you’ll still have some upfront expenses, such as earnest money, an appraisal, inspections, and certain closing costs. However, the VA limits some fees, and sellers can contribute toward closing costs, which often helps military buyers reduce their cash needed at closing in the Imperial Beach market.
How does my BAH factor into qualifying for a VA loan?
Lenders can typically count your Basic Allowance for Housing as qualifying income, which helps support a higher purchase price than your base pay alone might allow. Your loan officer will review your full income, BAH, and debts to determine a comfortable payment and price range for homes in Imperial Beach.